Step-by-Step Guide: How to fix inaccuracies in your credit report and improve your credit score?
 Gaadi Bazaar
 22 Oct 2026
 5 Min Read
 cars
 15 Reads
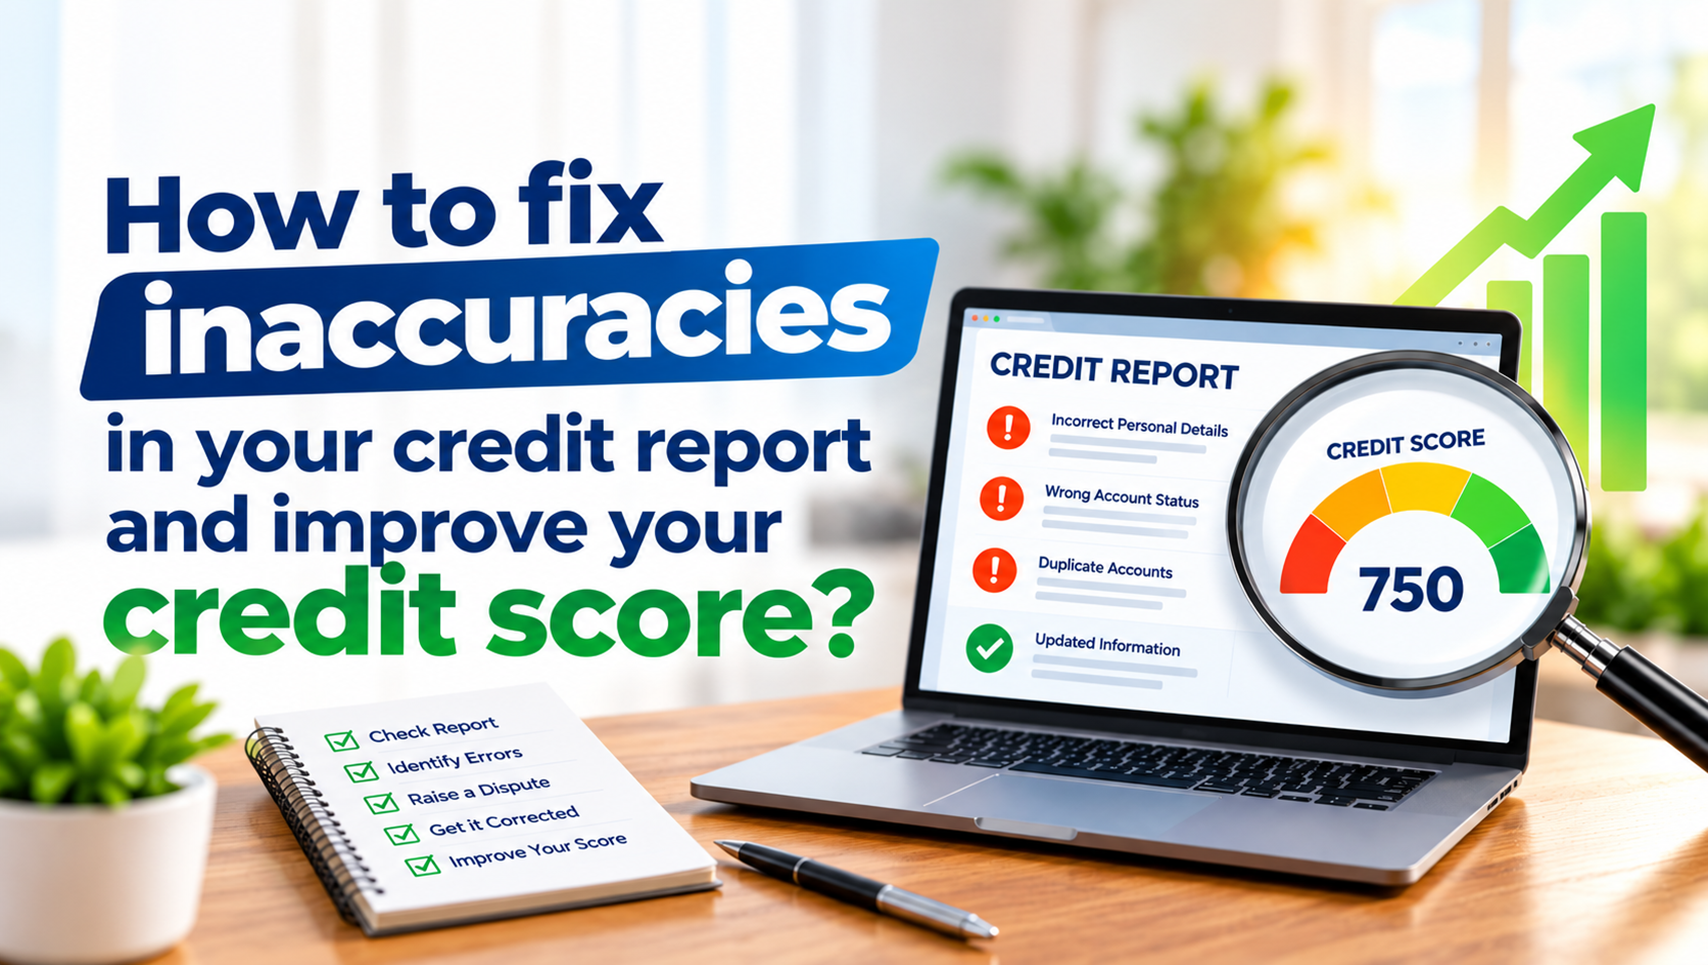
Table Of Content
- Introduction
- Audit the Hidden Details in Credit Reports
- Collect Evidence Before Filing Dispute
- Dual Correction in Bureau and Lending Institution
- Tips to Boost the Score
- Conclusion
Introduction
Does checking your credit score and finding a delinquent mark which you never had caused or even an open loan you have never taken triggers financial anxiety? Credit bureaus do not always run-on infallible databases. The bureaus are prone to errors too, even though it’s assumed that they have 100% financial logic. If a database is processing millions of batch data files every month, there is a huge possibility for clerical errors, delayed updates or identity mix ups too.
Now we understand that there can be errors in credit score given by credit bureaus. But are they negligible? No. These errors come with a cost of artificially inflating borrowing costs, in some cases even loan rejections. Months of good financial habit could be disrupted by the error not even caused by you.
Let’s see a step-by-step approach on cleaning the credit report and rebuilding the number.
Audit the Hidden Details in Credit Reports
Your full credit history is inspected by underwriters: repayment discipline, debt-to-income balance, active limits and past settlement remarks. If flawed data is reported by a lender, it cannot be fixed unless the exact location of the error is known.
Start by having your official credit reports pulled from all four licensed credit bureaus in India:TransUnion CIBIL, Experian, Equifax, and CRIF High Mark. Updates are not always reported to all four agencies simultaneously by lenders, meaning an error might be shown on your CIBIL report while your Experian file remains clean.
Once your complete files have been obtained, these four critical areas should be audited:
- Personal Details: Your legal name, date of birth, residential address and PAN number should be verified for complete accuracy. A "merged account" can be caused by a single typo in your PAN, resulting in someone else's unpaid loan being accidentally attached to your profile.
- Account Statuses: Every past loan and credit line should be reviewed. If a vehicle loan was cleared last year, the status should be checked to ensure it reads "Closed" with zero balance, rather than being erroneously recorded as "Written Off" or "Settled."
- Payment Track Record (DPD): A monthly payment track record (Days Past Due) is included with each account. Spotless streaks should be checked for. If your EMI was paid on time but was mistakenly logged as late by the bank, your score could be dragged down by 40 to 60 points by that single glitch.
- Credit Limit Mismatches: If a limit of ₹2,00,000 was sanctioned by your card issuer but was reported as ₹20,000, your everyday spending could be interpreted as an alarming 75% credit utilization instead of an ideal 7.5%.
Collect Evidence Before Filing Dispute
How many disputes are raised to credit bureaus? At least thousand. Most of those are automated like “Wrong Loan, Please Remove”. These are easily missed by the automated systems. To have a quick resolution, one must provide proper evidence.
Evidence includes:
- Bank statements
- NOC (No Objection Certificate)
- Identity Documents (PAN card, Aadhaar card or any Address proof)
- Dispute Summary containing lender name, loan account number, exact dispute issue and the expected correction
Dual Correction in Bureau and Lending Institution
Usually when there is a dispute is in credit report, it is raised to that particular credit bureau. Do you know where the actual data is created? It is created in the financial institution from which the actual loan was taken. So, if the records are not updated in that particular institution, the same is reflected in the credit report. The reason is data is not created by credit bureau; they are only the host.
In a case where you directly notify the credit bureau, it will again recheck with the lending institution. If the data is updated, it will be rectified. If it is wrong in the lending institution, the error will remain the same. So always double check the details first in your lending institution and resolve the same.
Always remember that customer queries should be disputed within 30 days based on RBI guidelines. If the lender is not providing valid proof for the error, it should be automatically corrected by the bureau in this 30 days’ time window.
Tips to Boost the Score
Once the error is erased, your baseline score will rebound. However, if vehicle financing is planned soon, a few extra steps can be taken to help you qualify for lower interest rates, reduced processing fees and better loan terms:
- Lower Your Credit Card Utilization: Your revolving card balances should be kept below 30% of your total credit limit—ideally below 10%. Card balances should be cleared a few days before the billing statement is generated so the reported balance remains minimal.
- Keep Seasoned Accounts Active: If an older credit card is rarely used by you, it should not be closed right before you apply for vehicle financing. A longer credit history is viewed by loan underwriters as a signal of stability.
- Pause Fresh Loan Inquiries: Every time you apply for a personal loan or credit card, a "hard inquiry" is initiated by the lender, which can temporarily lower your score. Multiple credit applications should not be submitted to different lenders within a short span.
- Maintain Strict EMI Timelines: Auto-debit (NACH) mandates should be set up on your bank account for all active EMIs. On-time repayment contributes roughly 35% to your credit score and demonstrates your ability to comfortably service new vehicle payments.
Conclusion
Your next vehicle should be seen as an exciting milestone, rather than a frustrating battle with financing paperwork. Poor financial management is not always reflected by a low credit score—often, it is simply caused by clerical errors and delayed banking updates.
By having your credit files checked a month or two before your vehicle is booked on Gaadi Bazaar, having proper documentation gathered and having disputes resolved early, the driver's seat is put in your hands. Faster loan sanctions, minimal paperwork hassles and the best possible EMI terms for your new ride are ensured by a clean credit profile.
Checking your own score is considered a soft inquiry and won't drop your points. CLICK HERE to check your CIBIL score for free without impacting your rating.
About the Author
 Gaadi Bazaar
Buying a vehicle is a big deal for many, and for all the right reasons. We are here only to make the whole process a whole lot simpler for you! India’s largest and most trusted vehicle marketplace, Gaadi Bazaar provides a comprehensive and wide range of new and pre-owned cars, bikes, trucks, tractors, and construction equipment – all under one roof, making buying and selling vehicles extremely convenient and updated! We are your automotive guide and we can help you pick and choose, for we believe in fulfilling your dreams – and we mean it! Enjoy a seamless and unchallenging experience with Gaadi Bazaar! The blogs on our website are written by professional writers who have extensive experience in blog writing specifically on vehicles and all things related to the automotive industry. The facts and figures mentioned are fact-checked and researched. Thank you for choosing Gaadi Bazaar for your automotive needs.
Latest Blogs from this Author
Blogs you might also like


Cars
Why You Should Regularly Check Your Credit Score?Review Your Credit Score Here is why it is important that you keep a close vigil on your credit scoreHere are the 4 main reaso...
22 Oct 20265 Min ReadGaadi Bazaar
Cars
IntroductionAchieving your financial goals might need assistance at time. Taking up a loan to buy a home or purchase a car or expand a business is a logical option for a lot of ...
22 Oct 20264 Min ReadGaadi Bazaar
Cars
Families take road trips to escape the hustle and bustle of the city, work stress and much more. A Road trip gives a sense of freedom and happiness to a modern-day family. But wha...
29 Jul 20263 Min ReadGaadi Bazaar
Cars
Whether you are a seasoned driver or a newbie, having your vehicle break down out of nowhere is truly a nightmare. What happens when you get stuck in a remote location with no acc...
29 Jul 20263 Min ReadGaadi BazaarConnect with us on


Looking to buy a used car?

6L+ Vehicles ✓ Trusted Sellers ✓ 100% Finance

Give us a missed call07941055729
07941055729Recently Posted Blogs





 Previous